
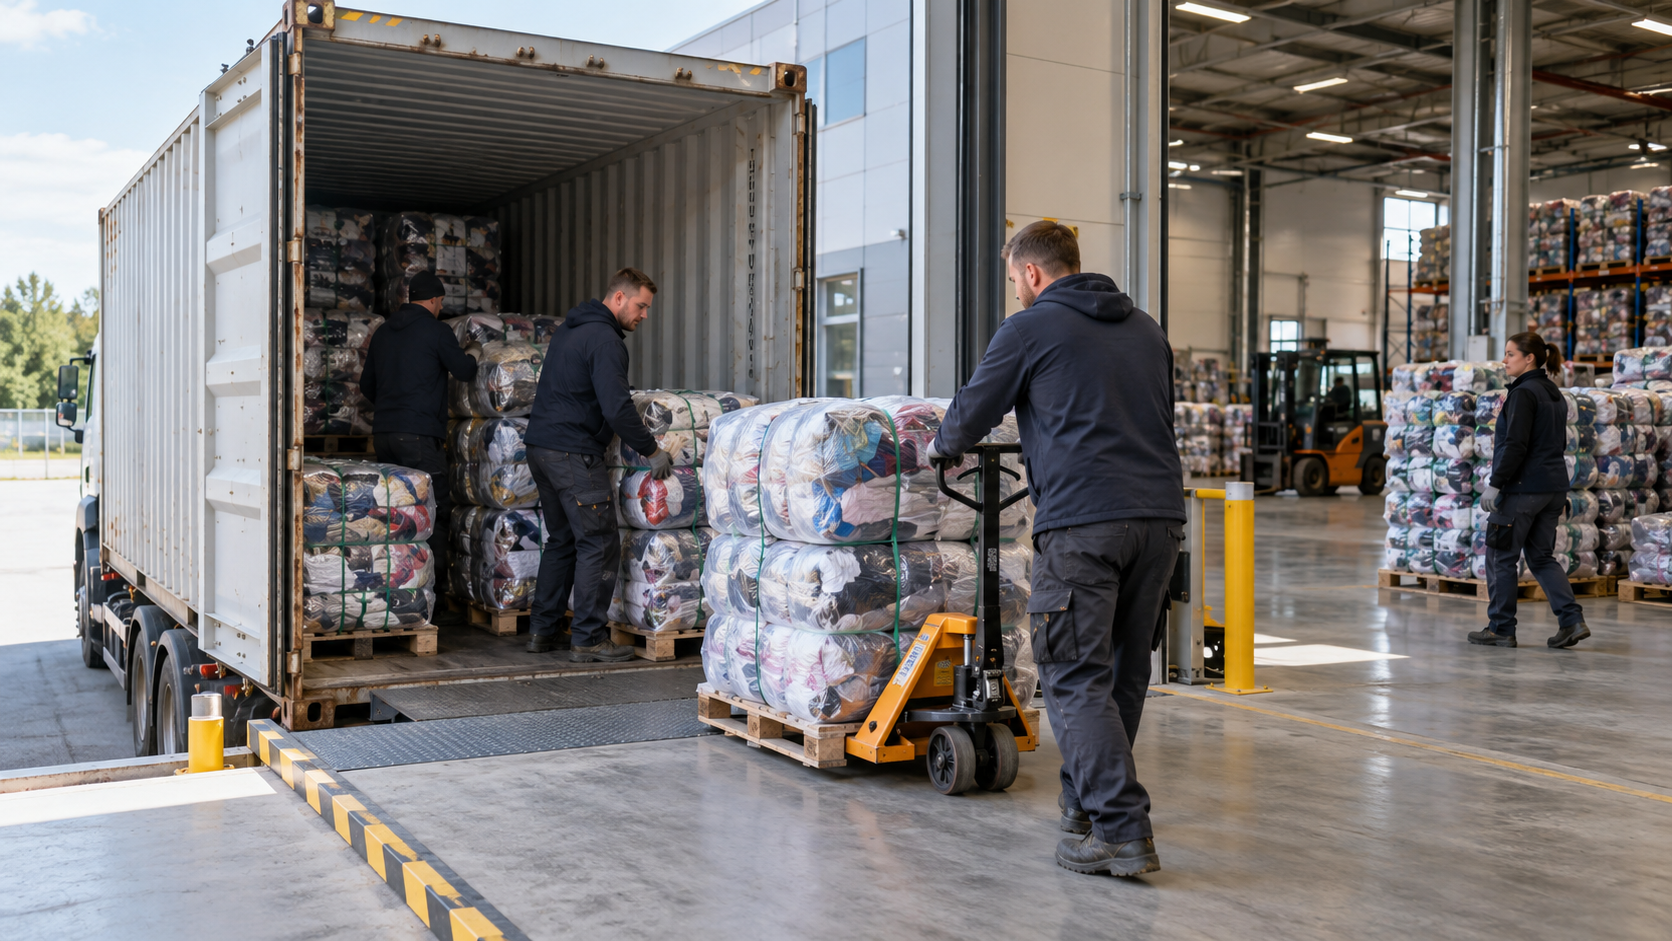
Used Clothing Import Logistics: How to Ship a Container to Poland
Importing a container of used clothing involves more than comparing the purchase price and freight cost. Container selection, proof of origin, customs duty, VAT, SENT and the boundary between goods and waste all affect the cost and organisation of the shipment. Supply origins should be compared on a cost-per-kilogram basis, while the sorting facility should be prepared for inspection and claims handling.

Key decisions before placing an order
Before purchasing
Define the specification, goods-versus-waste status, ability to demonstrate origin and claims procedure.
Before arranging transport
Confirm the loading plan, weights, bale dimensions, cost scope and the sorting facility’s capacity to receive the shipment.
Before dispatch
Check shipment readiness, documents, container condition, the method used to establish VGM and deadlines for providing data.
Before collection
Confirm releases, the carrier, SENT requirements, delivery booking, free-time conditions and container return arrangements.
On receipt
Inspect security seals, bale count, weight and quality according to the agreed method.
For a first container, it is better to start with the material specification and the capabilities of your own sorting facility, and only then choose the country of purchase and transport option. This report uses one common comparison point: clothing delivered, unloaded and accepted into a warehouse in Poland, before commercial sorting.
The model below structures the purchasing decisions. It is not an additional official procedure.
| Decision point | What should be agreed | Reason to stop before the next stage |
|---|---|---|
| Before making a purchase commitment | Specification, goods-versus-waste status, ability to demonstrate origin, claims procedure | The seller cannot document what is actually being sold |
| Before confirming transport | Loading plan, weights, bale dimensions, cost scope and sorting facility capacity | Profitability depends on an unconfirmed weight or unknown recovery yield |
| Before loading and dispatch | Shipment readiness, documents, container inspection, VGM method and deadlines for providing data | The documentation is inconsistent or the cargo does not match the specification |
| Before collection from the port | Releases, carrier, SENT obligations, delivery booking, free-time conditions and container return | The goods cannot be transported legally or unloaded on time |
| On receipt | Inspection of security seals, bale count, weight and quality according to the agreed method | A discrepancy requires isolation, a claim or clarification of the shipment’s status |
It is useful to maintain two calculations: cost per delivered kilogram and cost per kilogram qualified for sale. The first helps compare purchasing and logistics. The second shows the impact of material quality and sorting costs.
The sections below clearly distinguish legislation and official information, technical specifications, company declarations, and the report’s own recommendations and calculations.
1. First determine what you are buying: clothing for reuse or waste
“Unsorted” is not a sufficient specification
The purchase order should describe not only the commercial name of the material but also the process carried out before sale: collection source, inspection method, fractions removed and tasks left for the Polish sorting facility.
The proposed specification should determine whether footwear, handbags and household textiles are permitted, how soiling and damage are treated, and what the seller means by clothing prepared for reuse. Quality thresholds should not be set without considering the buyer’s ability to sell the material and manage the remaining fractions.
| Material description | Question that must be answered before purchase |
|---|---|
| Clothing prepared for reuse | How was the entire shipment checked for suitability and how was that inspection documented? |
| Material inspected but not commercially graded | Does further sorting concern sales categories, or is it still needed to recover usable items? |
| Unsorted material of undetermined composition | What is the material’s history, what has been excluded, and on what basis is it regarded as goods? |
| Textile waste for recovery | Which shipment procedure applies and what authorisations must the recipient hold? |
The table is intended for supplier qualification. It does not replace a legal assessment of a specific shipment.
An invoice and CN code do not remove waste status
The definition of waste refers to an object which the holder discards, intends to discard or is required to discard. The ability to sell it does not rule out waste status. Preparation for reuse of items that have become waste, and end-of-waste status, require separate assessment. [12]
A control authority may require documents demonstrating that the transported items are not waste. Protection against damage and, depending on the subject of the inspection, evidence of suitability are also relevant. The description “used clothing” alone does not settle the issue. [13]
Purchasing recommendation: before dispatch, link the shipment number to the specification, process description, photographic documentation and inspection results. If the status remains unresolved, stop the shipment instead of relying on the issue being clarified only once the container reaches the port.
When waste shipment rules must be applied
The main part of Regulation (EU) 2024/1157 applies from 21 May 2026. However, not all provisions have the same application date. [14]
For qualifying waste destined for recovery, the information procedure under Article 18 covers shipments over 20 kg and requires Annex VII and a contract. Not every unsorted shipment is green-listed waste or B3030 material. Imports from countries covered by the OECD Decision require the relevant import provisions to be applied; routing through another country may change the assessment. [13]
The contract should take account of the person arranging the shipment, the consignee and the operator of the facility where the consignee is not that operator. Before dispatch, the participants’ authorisations and the consistency of the documentation with the actual recovery operation should be checked. GIOŚ describes these requirements in its information on the green list. [16]
GIOŚ temporarily permitted paper Annex VII documents from 21 May to 31 December 2026, provided that the new form and contractual requirements are met. This is not an exemption from the procedure. For an international shipment, the requirements of the other competent authorities must also be confirmed; the Polish communication should not be treated as automatic approval for the entire route. [17]
2. 20′ or 40′ HC container: how much clothing can you actually load?
Three weights that must not be confused
For order control, keep the following separate:
Net clothing weight — the weight of the purchased clothing itself.
Cargo weight in the container — clothing plus packaging, pallets and securing materials.
VGM — the verified gross mass of the packed container, including its tare weight. IMO specifies either weighing the entire container or using an approved method that sums the individual mass components. [24]
Recommended control formula:
Cargo weight = net clothing weight + packaging + pallets + securing materials. VGM = cargo weight + tare weight of the specific container.
The weights shown on the invoice, packing list and transport documents do not necessarily represent the same measure. They should, however, be reconcilable.
Bales: check weight, quantity and geometry

GH Textile states bale weights of 45, 50 and 55 kg, while TESSO describes small bales of 45 kg and large bales of approximately 400 kg. These are formats offered by individual companies, not an industry-wide standard. [22]
| Arithmetic example only | Calculation | Total weight |
|---|---|---|
| 250 bales at 48 kg each | 250 × 48 | 12 000 kg |
| 500 bales at 45 kg each | 500 × 45 | 22 500 kg |
| 60 bales at 400 kg each | 60 × 400 | 24 000 kg |
These examples do not prove that the stated number of bales will fit into the selected container. All weights in a given calculation must be expressed on the same basis: either net or including packaging.
Arithmetic should also be checked in public offers. GH Textile describes a 40′ HC load as 25 tonnes and 580–600 bales, while also stating a minimum bale weight of 45 kg. Multiplication gives 26.1–27.0 tonnes. Such a discrepancy requires clarification from the supplier and an actual loading list, rather than using the more favourable figure in the budget. [22]
When is a larger container cheaper?
Own model: compare the full cost of arranging transport and collection for both options, divided by the confirmed net weight.
A 40′ HC has a lower logistics cost/kg when: 40′ HC logistics cost ÷ 40′ HC net weight < 20′ logistics cost ÷ 20′ net weight.
The cost boundaries must be identical. Do not compare the ocean freight alone for a 40′ HC with the full delivered cost of a 20′ container to the sorting facility.
A 20′ container can limit the capital required for a trial shipment and reduce the volume that must be received at one time. A 40′ HC may be more economical for volume-constrained material, provided the larger shipment does not exceed the sorting facility’s financial, storage and sales capacity. The decision should be based on the specific shipment, not on a general assumption that one size is always better.
3. CN, customs duty and origin: Canada, the USA, the EU and the United Kingdom
CN 6309 00 00 does not automatically cover every mixture of textiles
Heading 6309 covers specified worn articles. The HS note requires both signs of appreciable wear and presentation in bulk, in bales, sacks or similar packing. Baling alone is not sufficient; rags, clippings and other fractions require verification of the appropriate classification. [2]
Official information from the Dutch Chamber of Commerce, KVK, gives TARIC code 6309000000 and a basic duty rate of 5.3% for used clothing. This is a starting rate, not a determination for every shipment. Before customs declaration, the tariff measures applicable to the actual origin and clearance date should be checked. [1]
Importer action: provide the customs representative with a description of the contents, photographs, category proportions and packing method. Ask for confirmation of the classification and the basis for the duty rate applied. Where there is significant uncertainty, do not base the order solely on the code entered by the seller.
Canada: CETA requires origin, not merely shipment from a Canadian port
CETA allows preferential treatment for qualifying originating products. A warehouse in Canada or the collection of clothing there does not in itself prove compliance with the rules of origin. [3]
For HS 63.09, the product-specific rule provides for a change from another tariff heading. It must, however, be applied together with the provisions on insufficient operations. Simple sorting, cleaning, pressing or packing does not automatically confer origin. The rule concerning recovered materials from products suitable only for recovery is not a general basis for preferential origin for garments intended to be worn again. [4]
Under CETA, the proof is an origin declaration by the exporter, using the text in Annex 2, on an invoice or another appropriate commercial document. It is not an EUR.1 certificate. [4]
A Canadian exporter uses a Business Number where one has been assigned; CBSA guidance allows the relevant field to remain blank where no number exists. This does not remove the requirement to demonstrate origin. [5]
The EUR 6,000 threshold and REX registration above that amount concern an EU exporter in the relevant direction of trade. This mechanism should not be transferred to a Canadian seller. Proof of origin under CETA is generally valid for 12 months. [3]
Purchasing condition: the seller should present the basis for the origin of the specific shipment and be able to make supporting documents available in the event of verification. A statement that “the goods are Canadian” is not sufficient.
USA: zero duty rate and additional documentary requirements
From 1 July 2026, EU Regulation 2026/1455 establishes a 0% rate for covered goods originating in the USA. Annex I includes Chapter 63. The EU non-preferential rules of origin specified in the regulation apply on a transitional basis. This is not an automatic exemption for every product shipped from a US port. [7]
Implementing Regulation 2026/1422 introduced Article 59a. It also requires evidence of direct transport or that the goods remained under customs supervision during transport, storage or splitting of the consignment in a third country, subject to the specified restrictions on operations carried out on the goods. [8]
The European Commission explains that no single mandatory standard certificate of origin has been prescribed for this mechanism. An invoice alone, a “Made in USA” marking or a general certificate does not replace sufficient evidence. The importer should hold the required information when making the customs declaration. [10]
RFQ implication: ask the supplier to state the origin, provide documentation supporting that determination and disclose the full route. Transhipment through a third country must be reflected in the documentation as well as in the freight price.
United Kingdom: TCA preference does not remove customs clearance
Goods entering from the United Kingdom are imports. The TCA provides preferential treatment on the basis of an exporter’s statement on origin or importer’s knowledge supported by sufficient information. The statement uses the wording required by the agreement; a UK exporter provides the appropriate EORI number. For imports into the EU, the statement is valid for 12 months. EUR.1 is not used. [6]
A zero duty rate requires compliance with the TCA rules, which should not be equated with CETA. It does not remove the customs declaration or VAT accounting requirements. Special arrangements concerning Northern Ireland require separate assessment. [6]
Comparing origins without assuming that the country determines quality
| Origin | Tariff basis or status | What to compare before choosing |
|---|---|---|
| Canada | 0% where CETA and evidentiary requirements are met | Origin, full-route cost, shipment preparation, inventory in transit |
| USA | 0% for qualifying products under 2026/1455 | Origin, transport documents, current measures, transhipments |
| EU | No import customs clearance for goods with Union status | Price, delivery to warehouse, order size and correct VAT treatment |
| United Kingdom | 0% where TCA requirements are met; import formalities remain | Origin, customs clearance, crossing, transport and receipt |
Basis: CETA, Regulation 2026/1455, information on customs procedures and HMRC guidance. [3]
Analytical conclusion: there is no basis for choosing Canada solely on the comparison “Canada 0%, USA always 5.3%”. Nor should a uniform recovery yield, share of branded items or quality level be attributed to an entire country. This research did not identify representative data that would support such a comparison.
4. VAT and delivered cost: separate margin from cash requirements
The VAT taxable amount includes more than the clothing invoice
For a standard import of used clothing into Poland, 23% VAT generally applies. Article 30b of the Polish VAT Act covers the customs value increased by customs duty due and relevant incidental costs where these have not already been included. This includes, among other things, transport and insurance to the first place of destination, and also to another known place of destination in the EU. The same costs must not be added twice. [11]
If the documentation identifies the sorting facility as the place of delivery, the taxable amount should not automatically be cut off at the port. The first place of destination is determined from the documents; the Act also regulates cases where such information is absent. [11]
Worked example — not a commercial offer
Own assumptions: the correctly established customs value is PLN 100 000. Additional costs included in the VAT taxable amount, not previously included, are PLN 5000. Other potential charges are omitted. The comparison illustrates only the tax mechanism.
| Item | Scenario with 5.3% customs duty | Scenario with correctly applied 0% customs duty |
|---|---|---|
| Customs value | PLN 100 000 | PLN 100 000 |
| Customs duty | PLN 5300 | PLN 0 |
| Additional costs included in VAT taxable amount | PLN 5000 | PLN 5000 |
| VAT taxable amount | PLN 110 300 | PLN 105 000 |
| VAT 23% | PLN 25 369 | PLN 24 150 |
Calculation result: the difference in customs duty is PLN 5300 and the VAT difference is PLN 1219. Where VAT is fully deductible, the latter is not a permanent tax cost, although it may affect financing.
The right to deduct depends on statutory conditions, including the link between the purchase and taxable transactions. Article 33a allows qualifying taxpayers to account for import VAT in the VAT return where the required conditions are met. The chosen approach should be agreed with the accounting team and customs representative before import. [11]
Full cost per kilogram
Analytical model:
Delivered cost = goods + pre-carriage and export handling + freight and surcharges + insurance + customs duty + terminal handling and documents + customs clearance + inspections + storage and container charges not already covered + transport to the sorting facility + unloading and inspection + inventory financing + non-deductible VAT.
Each item should be marked as confirmed, conditional or missing.
Cost per delivered kg = delivered cost ÷ actual net weight of clothing delivered.
The denominator also includes clothing that will prove unsaleable only after sorting. It does not include pallets, packaging or undisclosed foreign articles. For a mixed shipment, the method used to allocate weights and costs should be described separately.
Cost per saleable kg = (delivered cost + sorting + management of remaining fractions + allocated selling costs) ÷ weight qualified for sale.
How a lower recovery yield changes the result
Own example, for illustration only: a 20 000 kg shipment has a total delivered cost of PLN 120 000. Additional sorting, residual-fraction and selling costs are assumed at PLN 20 000 for comparison. The assumption of a fixed cost is used to demonstrate the effect of the denominator — in reality, costs may vary.
| Indicator | 80% yield | 65% yield |
|---|---|---|
| Delivered weight | 20 000 kg | 20 000 kg |
| Saleable weight | 16 000 kg | 13 000 kg |
| Cost per delivered kg | PLN 6.00 | PLN 6.00 |
| Cost per saleable kg | PLN 8.75 | PLN 10.77 |
The cost indicator does not replace a margin calculation. The decision also requires the prices and weights of individual sales categories, revenues from other fractions and the actual costs of managing them.
5. Shipment preparation, documents and responsibilities
What to agree with the exporter
The recommended preparation scope includes shipment identification, inspection of contents, removal of non-compliant fractions, baling, weighing, package marking and documented loading.
Before the container is positioned, agree how its condition, cleanliness and dryness will be checked. Wet clothing should not be accepted merely on the promise that moisture absorbers will be used. Loading, securing and subsequent unloading arrangements should take worker safety into account, not only the use of available volume. The CTU Code also covers the unpacking stage of cargo transport units. [25]
A declaration of disinfection or fumigation should not be treated as universal confirmation of quality, origin or non-waste status. Any treatment requirements should be established for the specific cargo and transport operation.
Documents and the right time to check them
The table below is a proposed division of work.
| Document or information | What to check | When to check |
|---|---|---|
| Specification and claims arrangements | Categories, exclusions, inspection method, settlement of shortages | Before ordering |
| Commercial invoice | Parties, description, price, currency, delivery terms, shipment identification | Draft before dispatch; final version for declaration |
| Packing list | Number and markings of bales, net/gross weights, consistency of totals | After packing is completed |
| B/L or sea waybill | Carriage parties, container, ports, method of documentary release | Draft before the documentation deadline; issued document later |
| Road transport document | Consistency of the transport, consignee and place of delivery | Before the relevant leg begins |
| Origin documents | Correct mechanism and link between the evidence and the shipment | Basis before purchase; complete set before declaration |
| VGM | Method used, weight and responsible shipper | Before the carrier’s required deadline |
| Seal number and loading documentation | Link between the security seal, container and shipment | When the container is closed |
| EORI and customs representation authorisation | Correct identification and scope of representation | Before the declaration is handled |
| SENT or waste documentation | Correct obligation for the transport, not interchangeable forms | Before the movement covered by the requirement begins |
A packing list is not a transport document. The RFQ should also distinguish the weight used to settle the purchase from the weights used for transport purposes.
The shipper defined under IMO rules is responsible for providing the VGM. Without a VGM, the container should not be loaded onto the vessel. VGM does not, however, confirm the quality of the contents or their origin. [24]
A business carrying out customs operations should have the appropriate EORI number. Commercial documents form part of the material used for the customs declaration; they are not a substitute for it. [26]
Who performs each task and who bears the cost of an error?
Proposed organisational model:
| Area | Task owner to be identified in the contract |
|---|---|
| Composition, quality, weight and traceability of the shipment | Exporter, with the specification accepted by the importer |
| Booking, equipment, port deadlines and transhipments | Freight forwarder within the scope of the accepted instruction |
| VGM and transport data | Appropriate shipper and participants supplying the data |
| Classification, declaration and preferential treatment | Importer and customs representative within the agreed scope |
| SENT and transport data | Entities responsible for the relevant transport, with named persons or parties carrying out the tasks |
| Collection, unloading, inspection and equipment return | Importer, carrier and warehouse according to the schedule |
This allocation does not alter liability arising under the law or the form of customs representation. It should, however, make clear who corrects a document, by when it must be corrected and who is notified of a delay risk.
State the Incoterms rule in the contract together with the named place and edition. Separately define the point at which risk transfers, financing of individual transport legs, insurance and the claims procedure. Do not replace these arrangements with the general statement “transport included”.
For insurance, check the scope of cover for used clothing, exclusions related to the condition of the goods and packaging, obligations after a loss and notification deadlines. Receiving an insurance policy alone does not establish whether it covers the scenarios relevant to the buyer.
6. From order to sorting facility: use a timeline, not one number
No comparable, binding offers were obtained that would support one current number of days for all Canada–Poland or USA–Poland shipments. The report therefore does not provide a universal door-to-door transit time.
The Port of Hamburg describes the weekly AT-2/GEX-2 service with Montreal and Northern European ports. The stated 35-day cycle refers to the full service rotation, not delivery from a Canadian exporter to a warehouse in Poland. [27]
As historical data, Target Solutions’ experience importing via the Port of Halifax to Gdynia may be cited: on average, approximately 25 days of sea transport. [29]
Timeline to be completed by the parties
| Stage | Required information | What may delay the next stage |
|---|---|---|
| Accumulation and preparation of the shipment | Readiness date after quality inspection | Insufficient volume, rejected material, repacking |
| Booking and equipment | Confirmation of space and container positioning | No equipment or available space |
| Pre-carriage and export formalities | Terminal cut-off, document deadline and VGM deadline | Missing the cargo cut-off or data submission deadline |
| Ocean voyage | Planned departure and arrival dates | Schedule or connection changes |
| Each transhipment | Port, waiting time and onward leg | Missing the planned connection |
| Discharge and availability at port | Date when the container is available for collection | Inspection, missing documents, outstanding charges |
| Customs clearance and releases | Readiness of the declaration and removal of holds | Documentation discrepancies or need for clarification |
| Delivery, unloading and return of empty container | Delivery booking and return deadline | Lack of transport, staff, equipment or space |
Total-time calculation: add only stages that actually occur sequentially. Do not count parallel activities twice — booking may run while the shipment is being prepared, and import documents may be prepared before the vessel arrives.
When comparing routes, it is useful to request an option via a Polish port and an option via a Northern European hub with onward transport. For the United Kingdom, road transport with a crossing can be compared with a sea alternative, while EU purchases can be compared on the basis of road delivery. These are RFQ variants, not statements that a particular connection is available.
Purchasing rule: the vessel’s planned arrival date is not the container availability date and not the date on which the goods will be received by the sorting facility. Each of these dates should be confirmed separately.
7. SENT, port operations and checks after arrival

Current SENT rules for used clothing
From 20 June 2026, for CN 6309 00 00, the threshold for relevant transports to fall within SENT is more than 31.5 kg gross weight of the consignment. This is not the gross weight of the container including its tare. The former 10 kg threshold no longer describes the current rules. [18]
The type of transport and applicable exclusions must also be checked. A freight forwarder’s AEO status does not automatically exempt the party required to make the notification. The regulation contains detailed conditions covering, among other things, specified domestic transports, authorised entities and exceptions. [18]
PUESC explains that an import to the importer’s own warehouse in Poland may require SENT even under T1 transit. The customs procedure alone does not remove the obligation. [19]
Before collecting the container, determine who will make the notification, how the reference number will be provided to the carrier, which transport and location data are required, and how completion of the transport will be handled. Do not leave this for the driver to resolve at the terminal gate.
Customs release is not the only condition for collection
Release of goods for free circulation requires the appropriate customs release. Transit to an agreed place of clearance can be an organisational alternative, but it does not give the right to dispose of the goods freely before the relevant formalities have been completed. [26]
The collection plan should separately confirm customs status, the carrier’s documentary release, settlement of required charges and container availability at the terminal. A customs inspection does not replace commercial acceptance or analysis of recovery yield.
Demurrage, detention and storage
The operator’s conditions should be read before placing the order. In its information for Poland, Maersk distinguishes demurrage for the period from discharge until the full container leaves the terminal and detention until the empty equipment is returned. In the model described there, demurrage includes storage. This approach should not be transferred to every carrier, nor should the same cost automatically be counted twice. [28]
In the RFQ, require the start and end of free time, the method for counting days, the rates for subsequent periods and the correct location for returning the container. Separately request conditions for inspections, shifting, stripping and reloading, truck waiting time and document handling.
Do not assume that an inspection automatically stops charges from accruing. Their treatment should follow the applicable terms and contracts.
Recommended quality-receipt procedure
- Before opening the container, compare the container and seal numbers with the documents and take photographs. If the seal has been changed, first check the documentation of the inspection and resealing — a different seal number alone does not prove theft.
- Then count the bales, check their markings and record the weighing result together with the method used. Separate the weight of the clothing from packaging and other fractions.
- Quality inspection should follow a method agreed in advance, using material taken from different parts of the shipment. Assess compliance with the agreed categories, the condition of the packaging, moisture, odour, mould, contamination and unagreed fractions. Do not treat a few good items as proof of the quality of the entire container.
- If a hazard is suspected, isolate the shipment and follow the facility’s safety procedure. In the event of a commercial discrepancy, preserve bale traceability and documentation before further processing. Sample size, assessment criteria and the claims deadline should be agreed before dispatch.
8. RFQ and the shipment decision
How to obtain comparable quotations
The recommended RFQ to the exporter and freight forwarder should create one data package while separating responsibility for the goods from responsibility for transport.
| RFQ section | Information to provide or obtain |
|---|---|
| Shipment | Source, operations performed, categories, exclusions, shipment number, inspection and claims |
| Weights and packaging | Net/gross, number and dimensions of bales, meaning of declared bale weight, pallets, loading plan |
| Route and timing | Addresses, readiness date, ports, transhipments, place of customs clearance, destination sorting facility |
| Commercial terms | Price, currency, comparison exchange rate, validity, payment, Incoterms with named place and edition |
| Full logistics | Freight, surcharges, terminals, documents, inspections, onward delivery, unloading, equipment return |
| Formalities and risk | Origin, VGM, customs clearance, SENT or waste procedure, insurance, delays |
The comparison should end with a price for the same delivery boundary and the same method of calculating kilograms. Clearly identify costs already included in the exporter’s price.
Final recommendation for the sorting facility owner
Approve the shipment when you can link the specification to a specific shipment, support the adopted status and origin, agree the weight and transport plan, and finance the purchase even under a more conservative recovery-yield scenario.
Stop the shipment when profitability depends on an unresolved customs preference, inconsistent weight, unknown composition or omitted charges. A low purchase price does not solve these problems.
A trial shipment or inspection may help assess a defined supplier process. It should not be treated as an unlimited guarantee for all future deliveries. Where throughput is low and demand uncertain, compare a smaller purchase from a nearer market rather than assuming that the first purchase must be a full overseas container.
Sources
Verification date: 4 October 2026. The access date does not mean that every document was published or updated on that date. Company sources were used only for their own specifications, offers or terms.
Classification, tariffs and origin
- KVK, Kleding importeren — code and basic duty rate for used clothing; general passages on this page were not used to establish the current treatment of imports from the USA.
- CBSA, Customs Tariff 2026 — Chapter 63 — HS note on the scope of heading 6309; it is not the source for the EU customs duty rate.
- European Commission, Access2Markets, EU–Canada Comprehensive and Economic Trade Agreement — application of CETA and documentation of origin.
- Global Affairs Canada, CETA — Protocol on rules of origin and origin procedures — rule for 63.09, insufficient operations, origin declaration and annexes.
- CBSA, Memorandum D11-4-14 — exporter identification and origin documents.
- HMRC, Proving originating status and claiming a reduced rate of Customs Duty for trade between the UK and EU — statement on origin, importer’s knowledge and validity of the proof.
- European Parliament and Council, EU Regulation 2026/1455 — tariff treatment of covered products originating in the USA.
- European Commission, EU Implementing Regulation 2026/1422 — Article 59a and conditions for documenting transport.
- European Commission, Non-preferential rules of origin — non-preferential origin rules.
- European Commission, Q&A — UCC-IA Article 59a — clarification of evidentiary requirements, version dated 16 July 2026.
VAT, waste and SENT
- Polish Journal of Laws, VAT Act — consolidated text, Journal of Laws 2025 item 775 — Articles 30b, 33a and 86 and provisions concerning the standard rate.
- Polish Journal of Laws, Waste Act — consolidated text, Journal of Laws 2023 item 1587 — definition of waste and end-of-waste status.
- European Parliament and Council, EU Regulation 2024/1157 — consolidated version read as of 9 January 2025 — procedures, thresholds, documents and controls.
- European Commission, Waste shipments — current information on implementation and application dates.
- European Commission, EU clarifies rules to allow continued waste recovery shipments to Switzerland — scope of the later amendment applying from 30 July 2026.
- GIOŚ, Shipment of green-listed waste — organisation of the procedure and contractual requirements; thresholds were verified separately in the regulation.
- GIOŚ, Postponement of the DIWASS requirement for Annex VII documents — communication dated 17 April 2026.
- Minister of Finance and Economy, Regulation of 18 June 2026, Journal of Laws item 813 — current SENT threshold and exclusions.
- PUESC, SENT FAQ — clothing and footwear — imports to the importer’s own warehouse and transit.
Containers, transport and delivery handling
- Hapag-Lloyd, 20′ Standard — example specification.
- Hapag-Lloyd, 40′ Standard High Cube — example specification.
- GH Textile, Used clothing export — declared packaging and shipment parameters; the inconsistency identified in the report requires clarification.
- TESSO, Export of second-hand clothes — declared bale formats.
- IMO, Verification of the gross mass of a packed container — VGM and shipper responsibility.
- IMO, CTU Code and Cargo securing — technical principles for packing, securing and safe handling.
- Polish Ministry of Finance, EORI and Customs procedures — identification and basic import procedures.
- Port of Hamburg, AT-2/GEX-2 — service description, not an offer of transit time to a Polish sorting facility.
- Maersk, Poland — Import — published container handling terms and charges.
- Target Poland, Used clothing from Canada — commercial declaration concerning delivery organisation and the agency role.
Publication limitations
This text provides guidance to support importers of used clothing. The publication does not replace an individual customs, tax, environmental, legal or insurance analysis. The publication is available free of charge; all legal liability of the author is excluded.
FAQ
Does used clothing shipped from Canada automatically qualify for CETA?
No. The goods must have the required origin and the exporter must provide a valid origin declaration. A Canadian shipping address or warehouse alone is not sufficient.
Source: [4]Is EUR.1 required for EU–UK preferential treatment?
No. The TCA provides for an exporter’s statement on origin or importer’s knowledge supported by appropriate information.
Source: [6]What is the SENT threshold for used clothing?
For CN 6309 00 00, it is more than 31.5 kg gross weight of the consignment from 20 June 2026. The transport route and applicable exclusions must also be assessed.
Source: [18]How much clothing fits into a 40′ HC container?
There is no single weight for every shipment. The container specification sets the technical limits, but the actual load also depends on the bales, packaging, loading arrangement and route restrictions.
Source: [21]Does import VAT always increase the cost by 23%?
No. VAT may be deductible where the relevant conditions are met. The taxable amount, financing requirement and the possibility of applying Article 33a must be assessed separately.
Source: [11]Are an invoice and CN code enough to prove that a shipment is not waste?
No. The fact that material can be sold, or is simply described as “used clothing”, does not rule out waste status. Before dispatch, the specific shipment should be linked to the specification, process description, documentation and inspection results; if the status remains unresolved, the shipment should be stopped.
Source: [12] and [13]